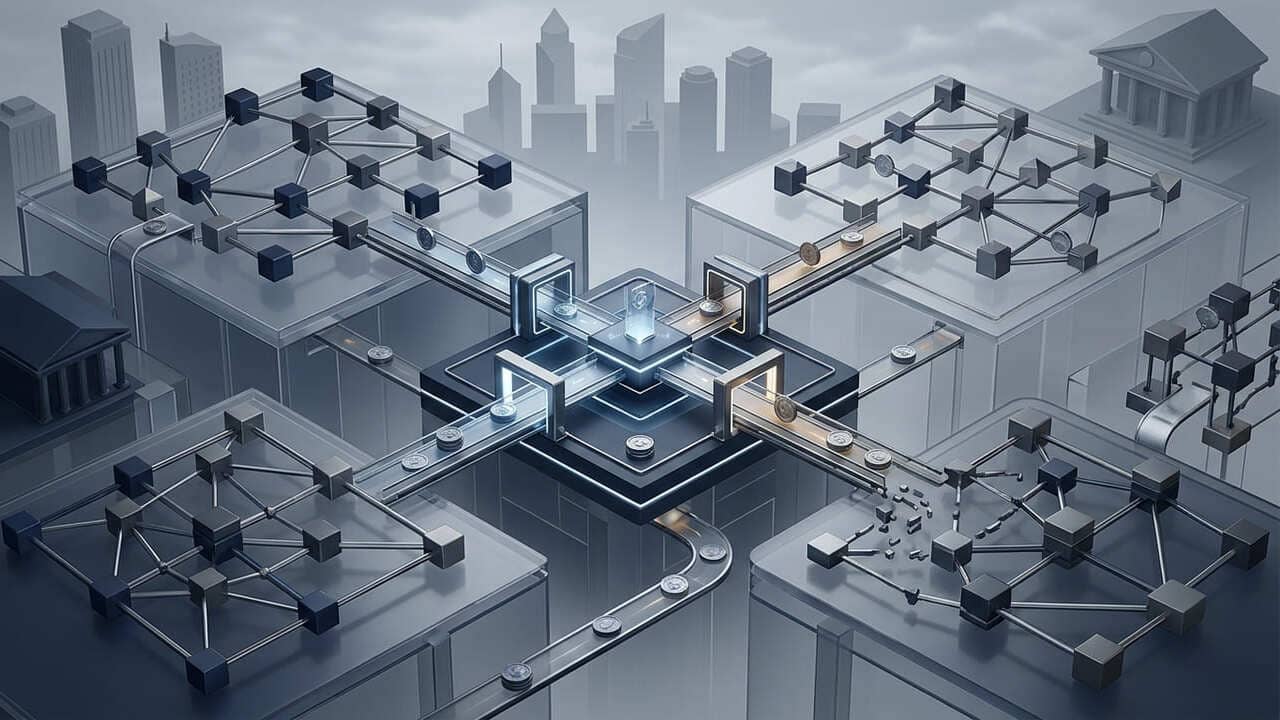
Cross-chain interoperability is becoming a central challenge for blockchain adoption as financial institutions and crypto platforms seek to move assets between networks without relying on complicated transfer processes.
Recent developments from Chainlink, Circle, Swift, and the European Central Bank show how the industry is addressing fragmented liquidity, slow settlement, and incompatible infrastructure. However, connecting blockchain networks does not automatically eliminate security risks or the operational dependencies that have complicated digital asset transfers.
The issue has gained importance as tokenized financial products expand beyond individual networks. Banks continue to need systems that can coordinate payments, securities, and collateral across different platforms. Meanwhile, crypto users still face additional fees, settlement delays, and potential losses when moving assets between blockchains.
Cross-Chain Interoperability Faces a Liquidity Fragmentation Problem
Blockchain networks usually maintain separate transaction records, liquidity pools, and settlement mechanisms. Consequently, assets held on one network cannot automatically move to another, even when both support tokens issued by the same company.
The Bank for International Settlements (BIS) identified this problem in a report examining blockchain infrastructure published on July 6. Researchers found that the expansion of Layer 1 and Layer 2 networks has fragmented assets and liquidity while introducing additional coordination challenges.
For example, USDC issued on Ethereum cannot move directly to Solana without supporting infrastructure. Users must rely on cross-chain transfer protocols, bridges, or exchanges to complete the process.
This breakdown can increase trading costs and reduce access to available liquidity. A decentralized exchange may hold substantial assets on one blockchain but lack sufficient liquidity to execute a comparable transaction elsewhere.
Institutional applications face additional difficulties. Banks transferring tokenized securities must coordinate asset ownership, settlement instructions, and compliance requirements across potentially incompatible systems.
Chainlink, Circle, and Swift Expand Cross-Chain Infrastructure
New interoperability developments aim to address these limitations through various technical approaches. On September 28, Chainlink announced CCIP 2.0, an updated version of its Cross-Chain Interoperability Protocol. The release described additional transaction verification options, configurable settlement speeds, and compliance controls designed for institutional digital assets.
Under the updated framework, financial institutions can configure independent cross-chain verifiers alongside existing verification infrastructure. This can allow organizations to impose additional checks before transactions execute on destination networks, depending on how the system is configured.
The protocol also supports configurable confirmation thresholds. Depending on the selected configuration, faster execution may involve accepting transactions before full blockchain finality is reached, introducing risks that institutions must evaluate.
Circle has pursued a different model through its Cross-Chain Transfer Protocol (CCTP). On September 2, Circle announced an expansion of CCTP to support native EURC transfers between Ethereum and Base. The system burns tokens on the originating blockchain and mints an equivalent amount on the destination network.
Unlike traditional liquidity-pool bridges, this approach does not require separate reserves of the transferred asset on both networks. Nevertheless, transfers still depend on supported networks, issuer-controlled infrastructure, and transaction verification.
Institutional adoption is also influencing interoperability development. In September, Chainlink announced work to connect financial institutions to Swift’s blockchain ledger using its Runtime Environment. The initiative is intended to let banks coordinate blockchain operations while retaining control of their transaction-signing keys. The announcement alone, however, does not establish that the integration is fully operational.
Separately, the European Central Bank announced the launch of Pontes on September 21. The infrastructure is designed to connect tokenized financial markets with existing Eurosystem payment services, allowing eligible wholesale transactions to settle in central bank money. The precise operational status and scope of the launch should be distinguished from the broader objective of the project.
Shared Standards Must Address Security and Infrastructure Risks
Technical interoperability alone does not guarantee reliable transfers. The proposed ERC-7683 cross-chain intents standard addresses another source of fragmentation: incompatible transaction instructions.
It establishes a common interface through which specialized execution providers, known as solvers, can interpret orders originating from different protocols.
Rather than requiring users to manage every step of a transaction, an intent-based application allows them to specify a desired outcome. However, ERC-7683 remains a draft standard. Its specification explicitly states that standardized order instructions do not guarantee the security of the underlying settlement mechanisms.
Past incidents demonstrate why that distinction matters. On April 18, attackers reportedly exploited KelpDAO’s LayerZero-powered bridge, releasing approximately 116,500 rsETH, valued at about $292 million at the time, through a forged cross-chain message.
Reports on the incident attributed the exploit to compromised infrastructure that supplied false blockchain information to a single-verifier configuration. LayerZero subsequently acknowledged shortcomings in allowing its verification service to operate without an additional independent check. These technical findings and the company’s response should be assessed in the context of the specific incident reports, rather than treated as evidence that all cross-chain verification systems share the same vulnerability.
My work focuses on cryptocurrency journalism, with more than four years of experience covering digital assets, artificial intelligence, and emerging technologies. I enjoy exploring the different sides of the crypto industry, from breaking news and market developments to the trends and innovations shaping its future.
I also write opinion pieces, technical analysis, and price predictions, adapting my approach to each topic and audience. Whether I’m explaining a market movement or examining a broader industry trend, I aim to deliver well-researched, engaging content that helps readers understand what is happening and why it matters