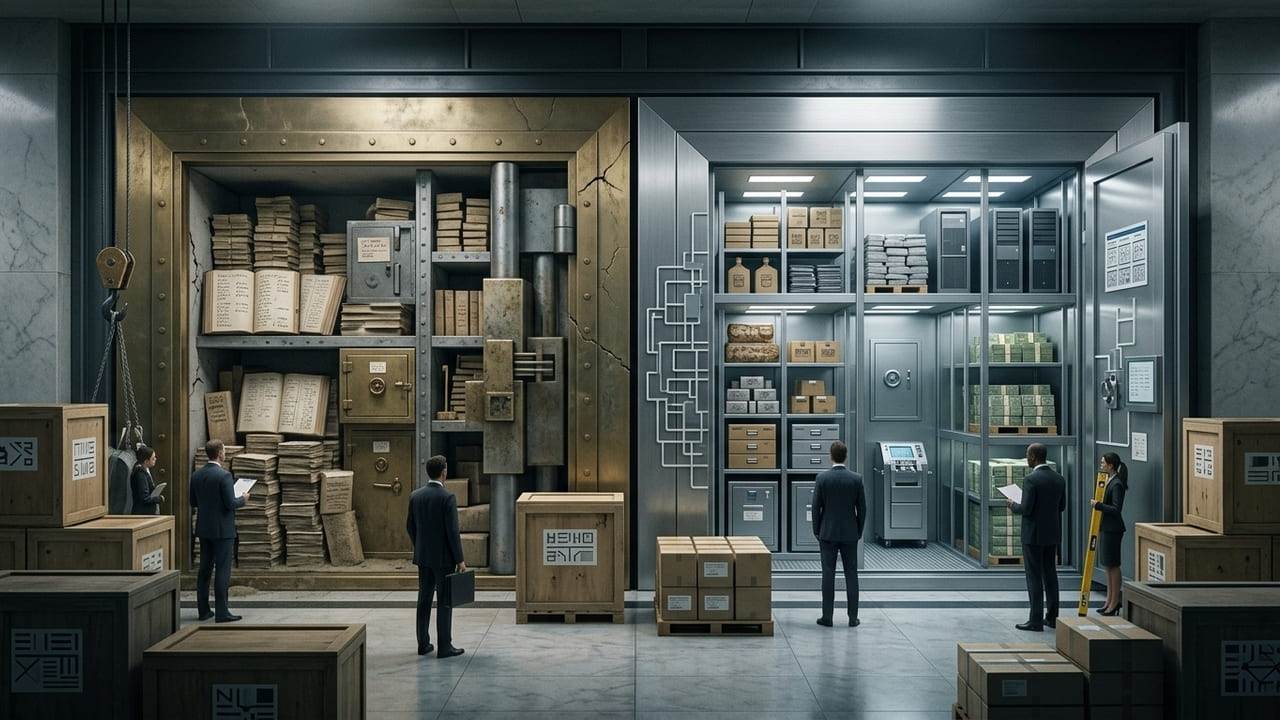
Total value locked has become DeFi’s favorite scoreboard. Protocols celebrate TVL milestones, rankings sort platforms by deposits, and markets often treat rising TVL as proof of strength. That approach is convenient, but it is also incomplete.
TVL tells the market how much capital sits inside a protocol. It does not explain whether that capital remains protected when markets fall, withdrawals accelerate, or collateral loses value.
A protocol can hold billions of dollars while carrying weak collateral, rising bad debt, or dangerously high utilization. Those weaknesses may remain invisible during calm periods. Once stress arrives, however, the difference between deposited value and recoverable value becomes much more important.
TVL Measures Size, Not Financial Strength
TVL still has value. It reveals adoption, liquidity, and the capital users commit. However, a large balance does not mean a healthy balance sheet. The KelpDAO incident showed that weakness clearly. In April, an attacker exploited KelpDAO for $292 million and created unbacked rsETH that entered lending markets as collateral.
The incident reportedly left around $200 million in bad debt across affected platforms. That means reported bad debt equaled about 68.5% of the exploit amount. That number tells far more about financial damage than TVL alone. A platform could still report billions in deposits while carrying losses that reduce what lenders can ultimately recover.
Aave provides another example. After the KelpDAO shock, the supplied data put Aave’s TVL near $15.3 billion, down from more than $45 billion beforehand. That represents a decline of more than 66%. Even that sharp TVL fall does not tell the full story.
Aave’s USDC market remained effectively at full utilization for four days. Repayments were absorbed by queued withdrawals instead of restoring usable liquidity. That means billions of dollars could remain inside the protocol while users still struggled to access available capital. This is where relying on TVL becomes misleading. TVL measures what sits in the system. It does not tell users how much remains liquid, how strong the collateral is, or whether outstanding obligations can be fully covered.
Solvency Answers the Harder Question
Solvency gets closer to the real issue because it focuses on asset coverage. A solvent protocol should hold enough valuable assets to meet its obligations. That sounds simple, but it forces markets to look beyond headline deposits and examine collateral quality, liabilities, bad debt, liquidation exposure, and reserves. That makes solvency more useful during periods of stress.
Still, solvency should not become another single-number obsession. A protocol can remain solvent on paper while suffering a severe liquidity shortage. Assets may exceed liabilities, but those assets may not be immediately available for withdrawals.
The Aave episode also shows why liquidity and solvency should remain separate measures. After the KelpDAO exploit, USDC utilization on Aave V3 Ethereum Core remained near 100% for several days, leaving little available liquidity for withdrawals. One governance proposal suggested steepening Aave’s interest-rate curve to attract fresh USDC deposits. However, subsequent community modeling showed the trade-off.
DeFi Needs a Better Health Dashboard
The answer is not to abandon TVL. The industry should simply stop treating it as a complete measure of financial strength. A better framework should combine several indicators. TVL should measure scale. Solvency should measure asset coverage. Utilization should show available liquidity. According to LlamaRisk, bad debt should reveal realized financial damage.
Collateral concentration should also matter because a protocol may appear healthy while depending heavily on one volatile asset. Liquidation capacity should measure whether markets can absorb forced selling without turning temporary price declines into permanent losses.
Stress testing should also become standard. Two protocols can each hold $10 billion in TVL and still have completely different risk profiles. One might have 60% utilization, diversified collateral, and 99% solvency. Another could have 95% utilization, concentrated collateral, and 90% solvency. TVL would rank them equally by size. Financially, they are not equal at all.
That is why solvency provides the better measure of DeFi resilience. TVL shows how large a protocol has become, but solvency shows whether that size can survive losses. DeFi should keep using TVL, but it should stop confusing size with strength. When markets become stressed, the real question is not how much capital entered a protocol. It is how much value remains available to cover what the protocol owes.
I’m a blockchain, Web3, and market news writer with more than five years of experience covering the cryptocurrency and fintech industries. My work focuses on turning complex market developments, product launches, data, and technical topics into clear and useful content. I regularly write about Bitcoin, Ethereum, DeFi, stablecoins, tokenization, ETFs, Web3 startups, fintech, AI, regulation, on-chain data, and market structure, combining news judgment with research and data-driven analysis.
Alongside daily news and market coverage, I have experience producing SEO articles, X threads, newsletters, research summaries, founder content, and social media posts. I also work on headlines, meta descriptions, and content designed for platforms such as Google Discover.